EXLUSIVE BUYER RESOURCE • SANTA CLARITA VALLEY & SAN FERNANDO VALLEY
The Assumable Advantage
Some homes in the valleys can still carry a rate you can't get today, Here's how assuming on really works — savings, costs, and all.
WHAT IS AN ASSUMABLE MORTGAGE?
You inherit the seller's rate – not today's.
When a home is financed with an FHA or VA loan, that mortgage is legally assumable. A qualified buyer can step into the seller’s existing loan — keeping the original interest rate and remaining balance. In today’s higher-rate environment, that can mean a meaningfully lower payment. Conventional loans don’t carry this benefit.
THE REAL NUMBERS
How Assumption Works – Step by Step
01
Quality with the Lender
Credit and income requirements must
still be met. The rate transfers — the
qualification does not.
02
Cover the Equity Gap
The difference between price and
remaining balance is paid via cash, a
second loan, or gift funds. This is
usually the largest hurdle — see typical
gap sizes below.
03
Seller's Lien Released
Once approved, the loan transfers into
your name. The seller is released and
the below-market rate is yours.
WHAT THE RATE DIFFERENCE CAN REALLY MEAN?
The honest numbers – gap included.
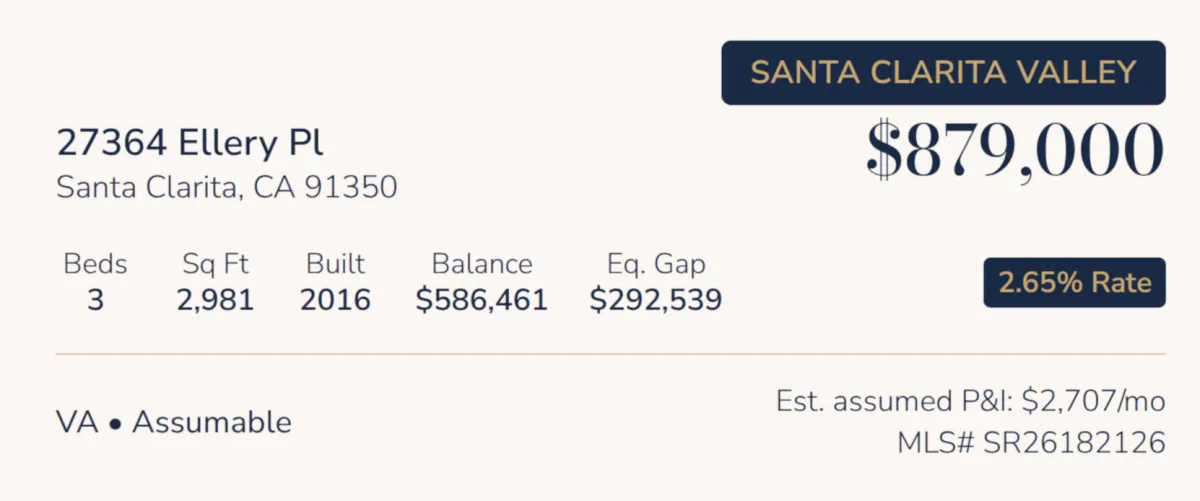
Using 27364 Ellery Place, Santa Clarita ($889,000) — a $177,800 down payment (20%) in both scenarios.
NEW LOAN TODAY
30-Year Fixed • 7.00%
$4,732/mo
On $711,200 loan (20% down)
ASSUMED RATE
Existing VA Loan • 2.65%
$2,707/mo
On existing $586,461 balance
Assuming the loan means taking over a $586,461 balance on an $889,000 home — there’s still a $124,739 gap left to cover beyond the same 20% down payment (a full-price buyer covers the entire $302,539 difference some other way; most cover part of it with a second loan). Here’s what the payment looks like once that gap is financed — and what it looks like if a buyer can cover it in cash.
Gap financed
(2nd loan,~9%, 20-yr)*
Gap financed
(2nd loan,~9%, 20-yr)*
Gap covered
In cash
Main assumed payment
~$2,707/mo
$2,707/mo
2nd-loan payment on the gap
~$1,122/mo
–
Total monthly payment
~$3,830/mo
$2,707/mo
Savings vs. the new 7% loan
~$900/mo
(~$10,800/yr)
$2,024/mo
($24,290/yr)
* Second-loan rate and term are an example only, not a quote. Every dollar borrowed — whether in the main loan or a second loan — is real debt.
Looked at as one blended loan, $586,461 at 2.65% plus $124,739 at roughly 9% works out to about a 3.76% blended rate on the full $711,200 borrowed
— still well below today’s 7%.
Figures are principal and interest only. Taxes, insurance, mortgage insurance, assumption fees, funding fees, and second-loan closing costs are
additional and vary by buyer. Gap financing availability and terms vary by lender; buyers must qualify for the combined payment. Confirm all figures with
a lender experienced in loan assumptions before making an offer.
A GLIMPSE AT WHAT'S AVAILABLE
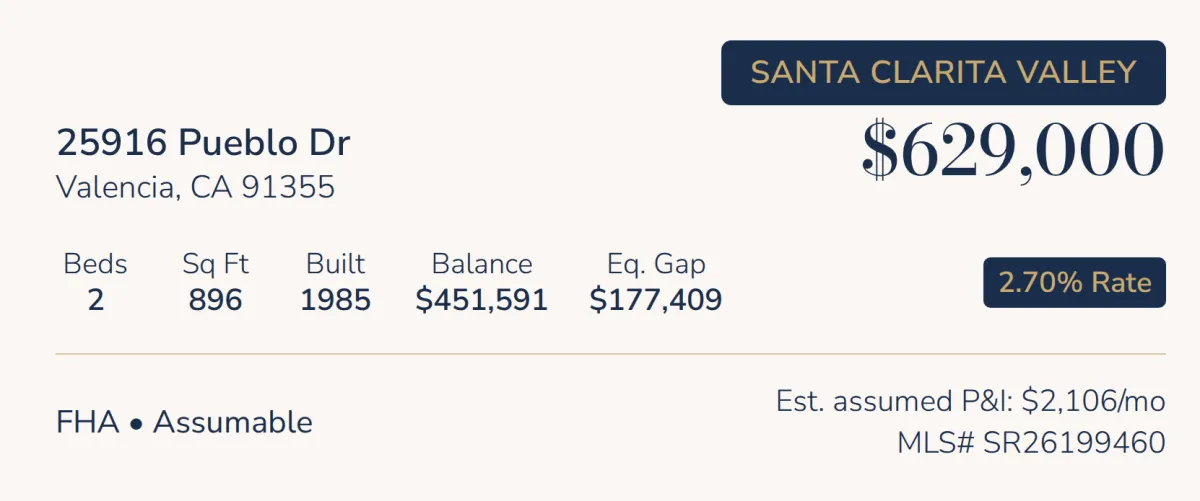
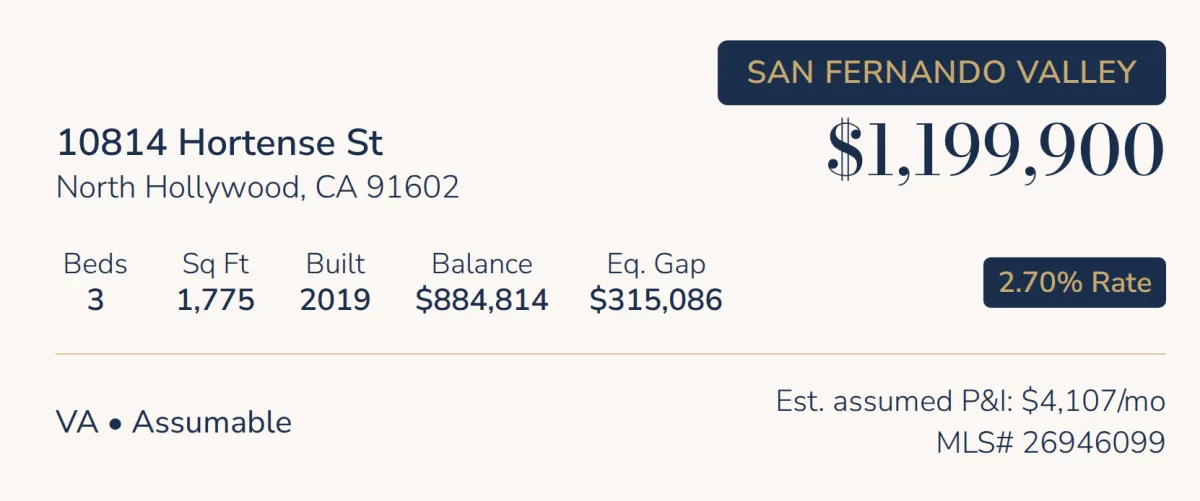
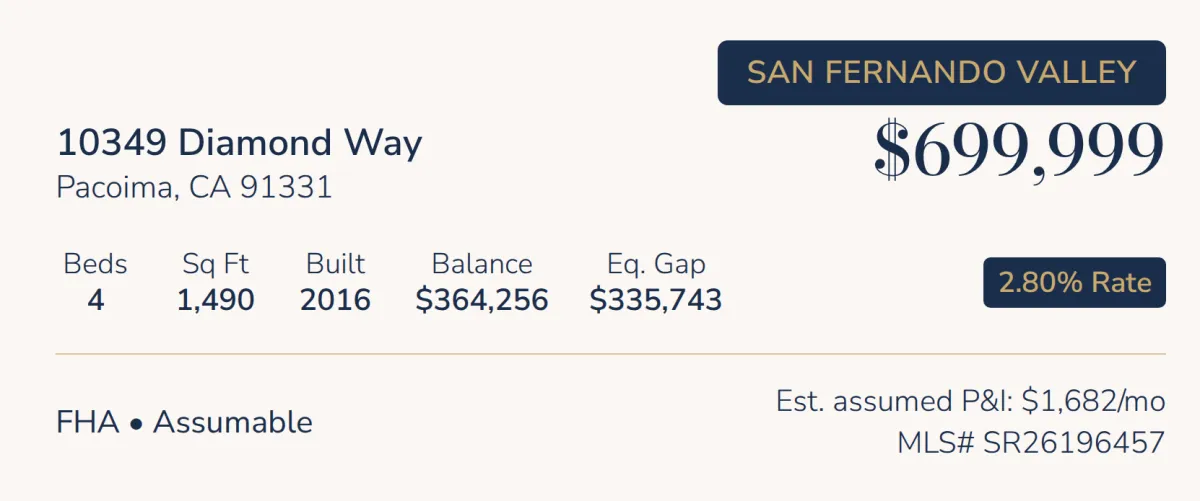
5 Samples Listing – SCV Assumable Mortgages
Assumable listings currently on the MLS across Santa Clarita & San Fernando Valley
Santa Clarita Valley
San Fernando Valley
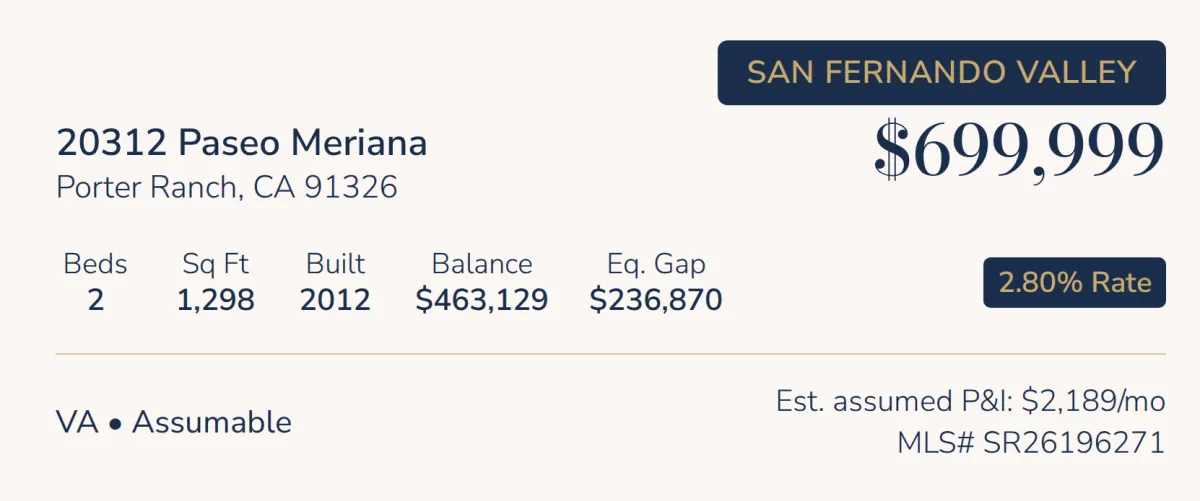
List accurate as of October 2026 · This list changes frequently — homes are added and go under contract regularly.
ASSUMABLE LOAN LISTINGS
Your Guide to Assumable Homes in either Valley
Get the free Assumable Guide, or book a quick call and I'll personally walk you through assumable homes available in both valleys.
🔒 Your information is 100% private. I will never share or sell it.
No pressure. No cold calls. Just honest conversation.
Reach me anytime at [email protected]
IMPORTANT TO KNOW
Before You Move Forward
• FHA loans are assumable by any qualified buyers. VA loans require lender approval – the seller forfeits their VA entitlement until restored.
• The equity gap (price minus balance) must be covered via cash, gift funds, or a secondary loan product.
• Not all sellers or listing agents know their loan is assumable. Having the right agent advocate for you matters.
• You must still qualify for credit and income – the rate transfers, not approval.
• Assumption timelines run 45-90 days – work with a lender experienced in assumptions.
• The list reflects active MLS data and changes often. Message me directly for the most current, complete version.
Rooted in Service. Built for Generation.